Dave: Credit, Cash & Money App

Screenshots
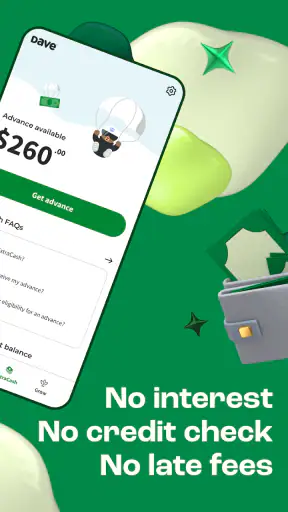
Details
- Rating
- 230.46K reviews
- Version
- 4.2.0
- Developer
- Dave Operating LLC
Analysis by Norviv
I find Dave most useful when a small, urgent expense arrives before income does. The key question isn’t whether an advance sounds convenient; it’s whether a short-term buffer fits your cash-flow habits without becoming something you depend on every pay cycle. I’d treat it as a backup tool, not as extra income or a replacement for a budget.
That distinction matters because short-term cash support can smooth over a timing mismatch, but it cannot make recurring expenses affordable. Before relying on an advance, I’d check what bills are due before the next payday and whether the repayment timing leaves enough for essentials. That quick check helps prevent today’s relief from creating a tighter week later.
Where it fits among money apps
Dave sits in a different lane from a conventional budgeting app. A budgeting tool mainly helps you understand and plan spending; a bank account is where you manage deposits and payments; Dave’s appeal is the combination of money-management guidance and access to a paycheck advance. If you only want spending charts, a budgeting app may be a better fit. If you need a cash-flow bridge once in a while, Dave is more directly aimed at that problem.
I would also compare it with the overdraft protection offered by your bank before making it a regular part of your routine. The useful comparison is not just whether one option feels faster, but what it costs, when money becomes available, and how repayment affects the next deposit. Those terms can differ, so I’d read the current details in the app and with my bank rather than assume every advance works the same way.
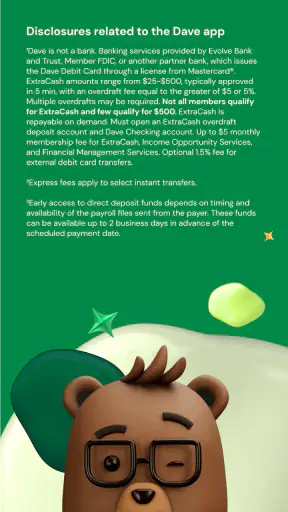
Dave is free to download, but that does not mean every part of using a financial service is necessarily cost-free. The app’s current version is 4.2.0, and its developer is Dave Operating LLC. I’d review the in-app terms for membership, optional tips, and any delivery choices before requesting money; costs and conditions are worth checking at the moment you use the service, not relying on an old summary.
A practical payday workflow
Imagine a utility bill is due a few days before your regular paycheck and your balance is too close for comfort. I’d first check whether the bill can be paid on its due date without a penalty, then look at my upcoming transactions and expected deposit. If an advance still seems appropriate, I’d request only enough to cover the gap, note how it will be repaid, and avoid treating the remaining available amount as spending money.
That order is a small but useful safeguard. An advance can solve a timing problem, yet the following payday may feel smaller because some of that money has already been committed. I’d use Dave alongside a simple calendar or bill reminder, especially if several automatic payments are scheduled close together. The app can help flag a low balance, but a personal list of upcoming obligations gives context a balance alert alone cannot provide.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
For someone with regular income and occasional surprises—such as a necessary household purchase or a bill that lands awkwardly between deposits—the app may be a practical reserve. Someone whose income changes week to week may find it harder to plan around repayment. In that situation, I’d prioritize a flexible budget and a small emergency fund where possible, and use an advance only after checking that the next deposit can cover both repayment and essentials.
Getting to Know Dave
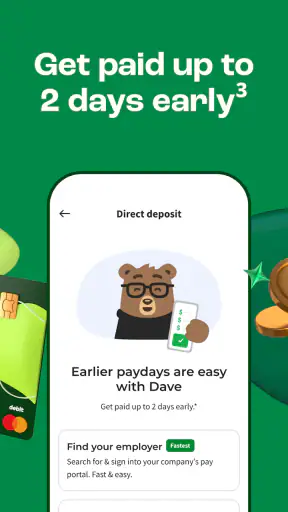
First off, Dave isn’t just a regular budgeting app. It’s designed to help you avoid those pesky overdraft fees that seem to pop up at the worst times. With a few taps, you can get an advance on your next paycheck, so you’re not caught off guard by unexpected expenses.
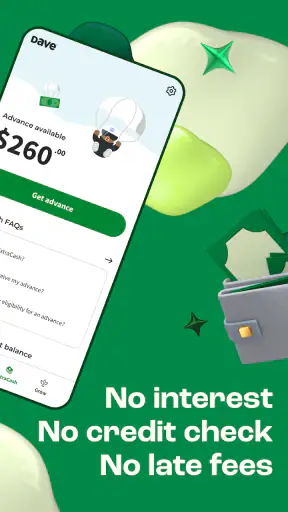
Signing up is pretty straightforward. You connect your bank account, and the app analyzes your spending habits. Don’t worry; it’s all secure and encrypted. Once you’re all set up, Dave acts as a safety net, offering cash advances up to $100. The best part? No interest rates or late fees, which is music to anyone’s ears!
Dive into the Features
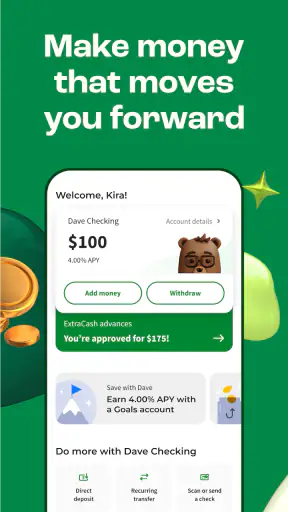
One of the standout features is the budgeting tool. It’s not just about borrowing money; Dave helps you manage what you already have. The app gives you insights into your spending patterns, highlighting areas where you might be overspending. It’s like having a financial advisor who doesn’t judge your coffee addiction.
Another cool feature is the notifications. Dave alerts you when your account balance is running low, so you can avoid overdraft fees. It’s proactive and helps you make smarter financial decisions. Plus, there’s even an option to plant a tree with every tip you give, making it an eco-friendly choice!
The Nitty-Gritty of Using Dave
Using Dave is as simple as it gets. The user interface is clean and intuitive, making navigation a breeze. Everything is laid out clearly, from checking your balance to requesting a cash advance. The app doesn’t bombard you with ads, which is a huge plus in my book.
But here’s the twist: while the cash advances are free, Dave does have a $1 monthly membership fee. However, considering the potential savings on overdraft fees, it’s a small price to pay. Plus, you can choose to give a tip for the service, which goes towards keeping the app running smoothly.
Readability and everyday access
For me, the clearest benefit of Dave’s layout is that the main money tasks are easy to distinguish: checking a balance, reviewing spending, and looking at an advance are not buried under a long menu. That matters when I’m dealing with a bill in a hurry. Still, financial screens can contain unfamiliar terms, so I’d slow down around any advance or repayment detail rather than tap through based on a quick glance.
If you have trouble reading small text or processing a busy screen, the practical test is whether you can comfortably review the figures and terms on your own device. I’d increase the phone’s text size or display scaling if needed, then check whether important amounts remain readable without excessive scrolling. Because this is a money app, clarity is more important than speed; if an amount or date is hard to interpret, I would not confirm a transaction until I could read it clearly.
Motor and sensory considerations
Dave is built around on-screen navigation, so it can be convenient for someone who prefers tapping through a focused set of tasks. But a cash request involves decisions where an accidental tap could matter. I’d use a steady connection, take my time, and review the amount and repayment information before confirming, especially if I have limited dexterity or use the phone one-handed.
Alerts can be helpful when I’m away from the app, but frequent or poorly timed notifications can also add noise. I’d keep only the financial reminders that help me act, and manage the rest through my device settings if they become distracting. Anyone who relies on sound, vibration, or visual cues should check how Dave’s alerts appear on their own phone and avoid assuming that one alert style will work equally well in every setting.
Situational access and who should look elsewhere
The app makes the most sense when I can securely access my bank account, review the relevant details, and anticipate a regular deposit. A shared phone, limited data access, or difficulty using banking credentials privately can make that workflow less comfortable. I’d set up or use the app only in a place where I can protect my financial information and take enough time to understand each step.
Dave is not the right answer for someone seeking a long-term loan, a way to erase persistent debt, or a budgeting system that can fix an income shortfall on its own. It may also be a poor match if connecting a bank account is a deal-breaker. In those cases, a bank’s own account tools, a standalone budget planner, or advice from a qualified nonprofit financial counselor may better address the underlying need. The app’s average rating is 4.6 from around 600,000 ratings, with roughly 230,000 written reviews and over 10 million installs, but popularity cannot tell me whether its terms suit an individual budget.
Remaining barriers and a careful first check
Before I rely on Dave, I’d confirm that my bank account connects properly and that I understand the timing and conditions shown for any advance. I’d also review the app’s current membership and optional-tip details rather than assuming an older description still reflects what I’ll see. A finance app can be straightforward to navigate and still require careful reading, particularly when access to money and repayment are involved.
It is rated for Everyone and was released on April 24, 2017, but those details do not guarantee that every person will find its screens or financial workflow easy. Dave is available for devices running OS 9 or later. I’d check that my device meets that requirement and that I can use its security and accessibility settings comfortably before depending on it for a time-sensitive bill.
There is also a difference between a low-balance alert and a complete plan. An alert can prompt me to act, but it cannot know which payment I should postpone or whether an upcoming expense is essential. I’d treat notifications as reminders, then make the decision with my own bill calendar and account information. That combination is more useful than expecting an app to interpret every personal circumstance.
What I would check before depending on it
A common question is whether someone can use Dave without an advance. The budgeting and balance-monitoring side may still be useful, but I’d explore the app’s current screens and terms to see what is available for my needs before making it part of a routine. If the only feature I want is a simple spending plan, I would compare it with a dedicated budget app rather than keep a financial product I do not use.
Another practical question is how much to request. My rule would be to ask only for the amount needed to bridge a specific, necessary expense, not the largest amount shown. I’d then write down the expected repayment date and account for it in the next pay period. That makes the trade-off visible before I accept the short-term relief.
For anyone worried about sharing bank information, I would not brush that concern aside. Linking an account is part of the described setup, so the decision should depend on your comfort with connecting financial data and the protections and terms you review in the app. If you are not comfortable with that arrangement, your bank’s own balance alerts or a manual budget may be a better fit, even if they do not offer the same cash-advance workflow.
What You Might Not Love
Now, let’s keep it real. Dave isn’t a solution for long-term financial problems. It’s a temporary fix, so if you’re consistently relying on cash advances, it might be time to reevaluate your budget. Also, the app works best if you have a regular paycheck; freelancers or those with irregular income might not find it as useful.
The app also requires access to your bank account, which could be a concern for some users. Although it’s secure, sharing financial data always comes with a bit of risk.
Final Thoughts
In the end, Dave: Credit, Cash & Money App is a handy tool for anyone who needs a little extra help between paydays. It’s user-friendly, effective, and offers peace of mind when unexpected expenses arise. While it’s not a one-size-fits-all solution, it does what it promises: helping you avoid overdraft fees and manage your finances better.
So, if you’re tired of those sneaky bank fees and need a financial buddy, give Dave a try. It might just be the app you didn’t know you needed.
My inclusive verdict is that Dave can be approachable for people who want a direct route to balance checks, spending awareness, and occasional short-term help, provided they can comfortably read the terms and use the connected-account setup. I’d recommend it most to someone with predictable income who treats an advance as a rare bridge and checks the repayment impact first. For anyone who needs more control over text, input, or financial privacy than the app-and-bank workflow offers, a bank’s built-in tools or a simpler manual plan may feel more dependable.
Frequently Asked Questions
01What is Dave: Credit, Cash & Money App used for?
Dave: Credit, Cash & Money App is designed to help users manage their finances more effectively. It offers features like budgeting tools, cash advances, and credit building options. The app aims to prevent overdrafts and provide users with the financial insights they need to make informed decisions.
02How does Dave's cash advance feature work?
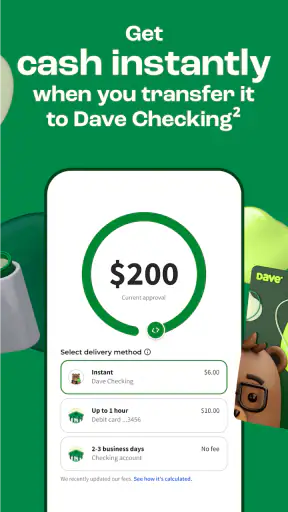
Dave offers a cash advance feature that allows users to borrow a small amount of money until their next paycheck. This service is designed to help cover unexpected expenses without the high fees typically associated with payday loans. Users can request an advance through the app, and funds are usually delivered within a few business days.
03Does Dave have any subscription fees?
Yes, Dave operates on a subscription model. Users are charged a small monthly fee to access its services, including budgeting tools and cash advances. It's important to verify the current subscription cost on the app, as this fee supports the development and maintenance of the application.
04Is Dave safe to use for managing finances?
Dave is considered safe for managing your finances, as it uses encryption and security protocols to protect user information. However, users should always ensure they are downloading the app from a legitimate source and regularly update their passwords to maintain security.
05Can using Dave improve my credit score?
Dave offers a feature called Credit Builder, which helps users improve their credit score over time. By reporting on-time payments to the credit bureaus, users can gradually build or improve their credit history. This can be a valuable tool for those looking to establish or enhance their financial standing.


